For group CFOs with a branch or subsidiary in Italy
Your Italian entity’s VAT, taxes and credits as the Revenue Agency sees them, on your desk every month.
FiscalPulse reads the Cassetto Fiscale of your Italian branch or subsidiary, its tax drawer at the Agenzia delle Entrate, and gives you VAT, income taxes, credits and payments as an assessor would see them: the declared figure where one exists, with document and year beside it, and an estimate only where needed. In English, on fixed dates.
€29 a month per Italian entity · read-only access · groups following 100 companies or more: demo
 Sample company · illustrative data
What you read every month
Cash, taxes and board evidence, seen from the Italian side
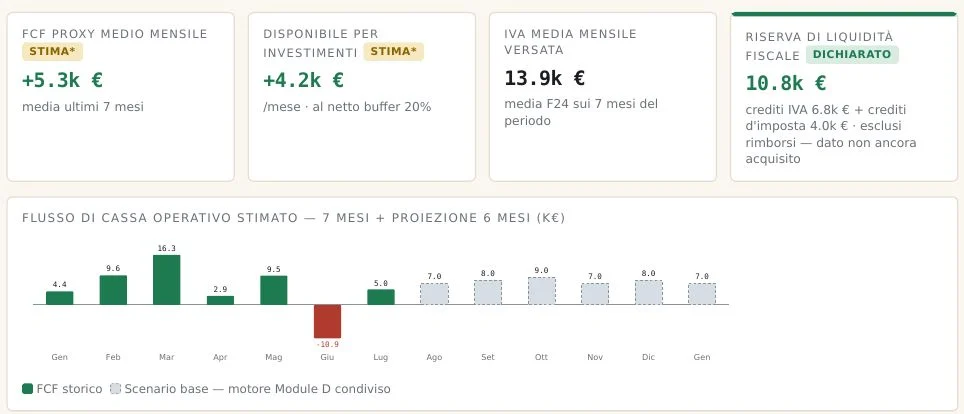
VAT credits and refunds, offset or withheld
VAT credits, tax credits and refunds in a single reserve.
Read more
Credits withheld, blocked by an administrative hold (fermo amministrativo) or offset against a debt still open elsewhere are clearly marked. That is cash the entity can free up without selling anything more.
Cross-border purchases
€120.0k
TD17 services from abroad €84.0k · TD18 intra-EU goods €36.0k · TD19 €0
VIES status
active
Sample company · illustrative data
Intercompany and cross-border flows as the Italian tax system records them
Services bought from abroad, recharges from the parent and intra-EU goods all leave a trace in Italian e-invoicing as reverse-charge documents (TD17, TD18, TD19).
Read more
The report totals them by type alongside the entity’s VIES status, so flows with the rest of the group are visible from the Italian side too.
VAT, IRES and IRAP projected six months ahead
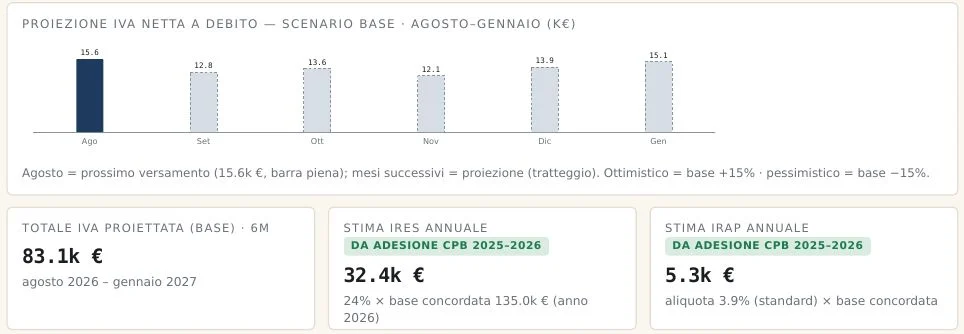
The next VAT payment, a six-month VAT projection on a seasonal basis, and IRES (corporate income tax, 24%) and IRAP (regional tax, standard 3.9%) calculated on the income agreed with the Agenzia when the entity joined the two-year advance agreement on taxable income (concordato preventivo biennale, CPB).
Read more
Your group forecast starts from Italian numbers that hold.
Declared VAT arrears and leverage, before a bank reads them
Section VQ of the annual VAT return records VAT declared and left unpaid in earlier years, a debt an Italian bank only sees much later.
Read more
Interest expense from line RF118 and equity from section RS of the corporate tax return complete the picture: you read them first.
Declared figures checked against the documents
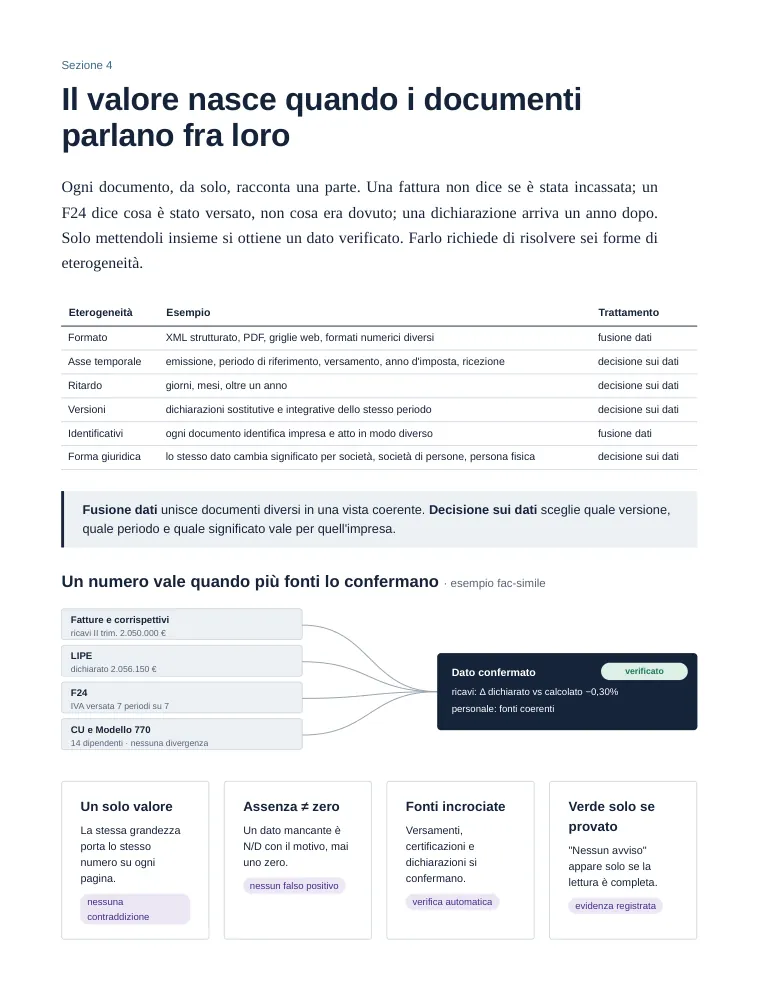
The LIPE (quarterly VAT return) against invoices and receipts, the CU employee certificates and the 770 withholding return against F24 payments (the single form for Italian taxes and contributions): the gap is measured entity by entity, and every number carries a badge saying where it comes from.
Letters and deadlines on page one
Every letter from the Agenzia as soon as it appears in the Cassetto Fiscale, with the amount contested, the difference and the date to settle, explained in English.
Read more
An avviso bonario (the Agenzia’s notice of irregularity) paid within 60 days carries a third of the penalty. Found late, it costs the full penalty.
Headcount and payroll cost from CU and F24
Headcount counted from the CU certificates, one for each employee, and payroll cost rebuilt from monthly F24 contributions and checked against the 770 return.
Read more
Group HR and budgeting get Italian figures confirmed by two independent sources.
The evidence your board and statutory auditors ask for
Article 2086 of the Italian Civil Code requires adequate organisational arrangements (adeguati assetti) to detect a crisis in time.
Read more
A monthly register of early-warning indicators documents them, with an alert as overdue VAT approaches €20,000, the level above which the Agenzia must notify the company and its board of statutory auditors, if it has one.
An Italian entity, seen from group finance
Paolo, the founder, shows what headquarters sees every month.
Data fusion
The numbers exist. The Cassetto Fiscale already holds them in one place.
Invoices in the local accounting system, F24 payments from the accountant, returns at the accountant’s office, letters in the PEC certified mailbox: each source tells part of the story.
Read more
The report cross-checks them: each payment against what was due, each return against the invoices of the same period.
Sample company · illustrative data
Activate the report on your Italian entity
We need the entity’s Entratel or Fisconline credentials, or one of our partner accountants in Italy appointed for read-only access. If the credentials have to be requested, we do it together through the company’s PEC certified email, and they arrive in four to seven days. Activation takes about half an hour. The local accountant keeps doing their job and can receive the report in copy.
Groups following a hundred companies or more: a demo on your own positions.
Over 2,000 invoices a year, or job costing by project: a proposal sized on your volumes.
Questions
Does the report use declared data or estimates?
It uses the declared figure whenever one exists and names the source. VAT from the LIPE and the annual VAT return, income taxes from the tax return or the agreed CPB income, payroll from F24, CU and 770. Where an estimate remains, it is marked as such, so group finance knows which Italian numbers are final.
What does section VQ of the Italian VAT return show?
It shows VAT declared and left unpaid in previous years, and how much has been recovered since the return was filed. A bank sees this debt to the Italian State much later. The report shows it now, together with the recovery payments, so group finance can plan for it.
How are IRES and IRAP calculated if the Italian company joined the concordato preventivo biennale?
On the income agreed with the Agenzia for the two-year period, which replaces the estimate. The report separates the IRES already paid in the year, on a cash basis, from the annual tax on an accrual basis: they are two different numbers and are not expected to match.
Can we see the Italian entity’s purchases from abroad?
Yes. Services bought from abroad, intra-EU goods and the related reverse-charge documents are totalled by type from Italian e-invoicing, next to the entity’s VIES status. Group finance sees cross-border flows as the Italian tax system records them, period by period, in the same report as the entity’s VAT returns and tax payments.
Does it work for a group with several Italian companies?
Yes. Each company activates its own access and receives its own report, at €29 a month per company up to 2,000 invoices a year. For groups following a hundred companies or more, we prepare a demo on your positions. Above 2,000 invoices a year, we send a proposal sized on your volumes.